
Why You Should Care About the Japanese Yen in Crypto
If you have been watching the cryptocurrency market, you know that volatility is not just a feature; it is the entire game. Bitcoin can swing 400% in a year. Ethereum follows suit. For most people, this wild ride is exciting but also terrifying for everyday use. Now, imagine trying to buy coffee or pay rent with an asset that might be worth half as much by tomorrow. That is where stablecoins come in. They are designed to hold their value steady, usually pegged to fiat currencies like the US Dollar.
But what if you live in Japan? Or what if your business deals heavily in Japanese Yen? Until recently, there was a glaring gap in the market. Major stablecoins like Tether (USDT) and USD Coin (USDC) are dollar-backed. If you are a Japanese user wanting to enter the decentralized finance (DeFi) world without converting your yen into dollars first, you faced friction. Enter JPYC Prepaid, often referred to simply as JPYC. This is not just another meme coin hoping for hype. It is a specific financial tool built to solve a very real regulatory and practical problem in one of the world's largest economies.
In this guide, we will break down exactly what JPYC is, how it maintains its peg to the yen, why it exists under such a strange legal classification, and whether it is actually useful for you today. We will look at the technology behind it, the risks involved, and how it compares to other options available in 2026.
Defining JPYC: More Than Just a Token
Let’s get the basics out of the way. JPYC Prepaid is a digital asset pegged 1:1 to the Japanese Yen (JPY). When you hold one JPYC token, you should theoretically have the purchasing power equivalent to one physical yen. But here is the catch: calling it a "stablecoin" in Japan is legally tricky. In fact, for years, it wasn't allowed to be called that at all.
To understand JPYC, you need to understand its legal wrapper. Under Japanese law, specifically the Payment Services Act, issuing traditional stablecoins was heavily restricted until June 2023. Even then, only banks and trust companies were allowed to issue them. So, the creators of JPYC had to get creative. They structured JPYC as a Prepaid Payment Instrument. Think of it like a digital gift card or a prepaid debit balance, but instead of sitting in a bank account, it lives on the blockchain.
This distinction matters because it defines who can use it and how. It allows individuals and businesses to acquire JPYC through bank transfers and then move those tokens freely within the crypto ecosystem. It bridges the gap between traditional banking systems and decentralized networks. Launched in January 2021, JPYC grew rapidly, becoming a multi-million dollar issuance project in less than six months. It was backed by Circle Ventures, the same entity behind USDC, which added significant credibility to the project early on.
How Does JPYC Stay Pegged to the Yen?
The biggest question with any stablecoin is: "What backs it?" If the backing disappears, the peg breaks, and you lose money. JPYC avoids the risky algorithmic models that caused collapses in the past (remember Terra/Luna?). Instead, it relies on hard assets.
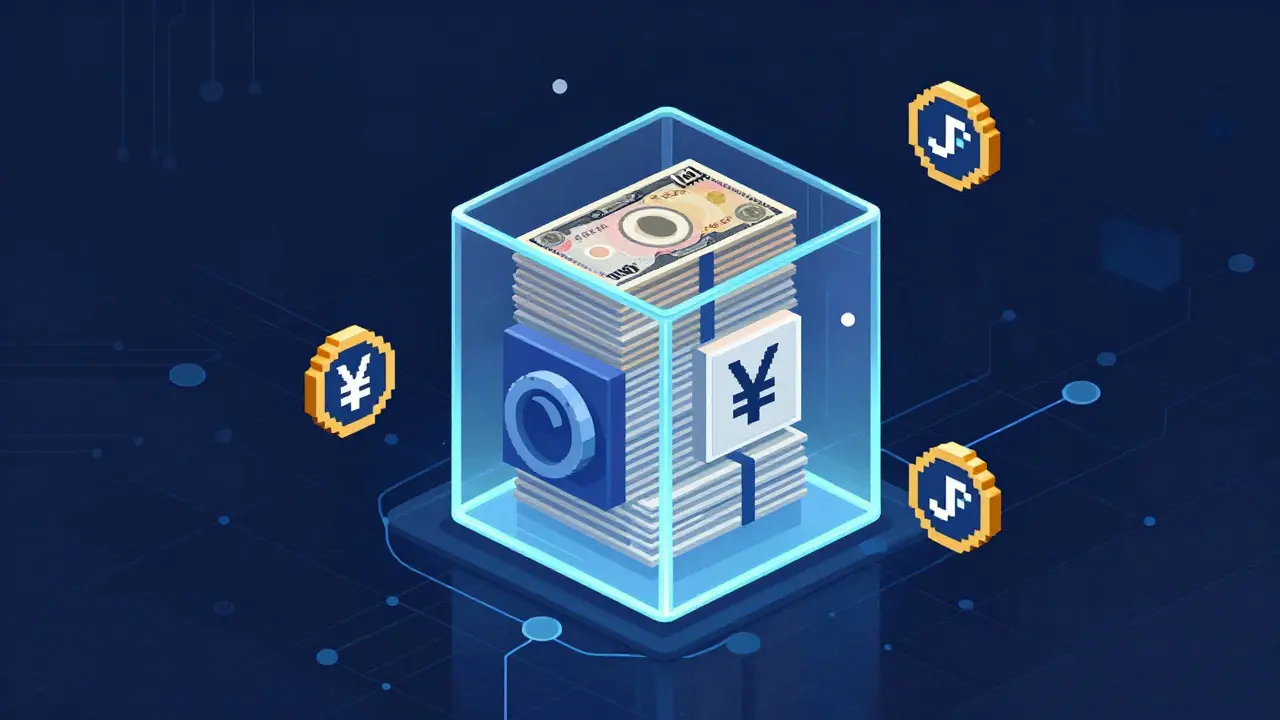
Every JPYC token in circulation is backed by liquid reserves. These reserves primarily consist of:
- Bank Deposits: Actual cash held in regulated financial institutions.
- Japanese Government Bonds (JGBs): Low-risk government debt instruments.
This structure ensures that for every token minted, there is real-world value sitting in reserve. The mechanism is straightforward: when you want JPYC, you send yen to the issuer via bank transfer. The issuer mints new tokens and sends them to your wallet. When you want your yen back, you burn the tokens, and the issuer releases the corresponding funds from the reserve.
This creates a closed loop. The supply adjusts based on demand. If everyone wants to sell JPYC for yen, the supply decreases. If everyone wants to buy JPYC, the supply increases. This dynamic keeps the price hovering tightly around $0.0072 USD (depending on the current exchange rate of JPY to USD). As of March 2026, JPYC has maintained this stability effectively, trading with minimal deviation from its peg.
The Technology Behind the Scenes
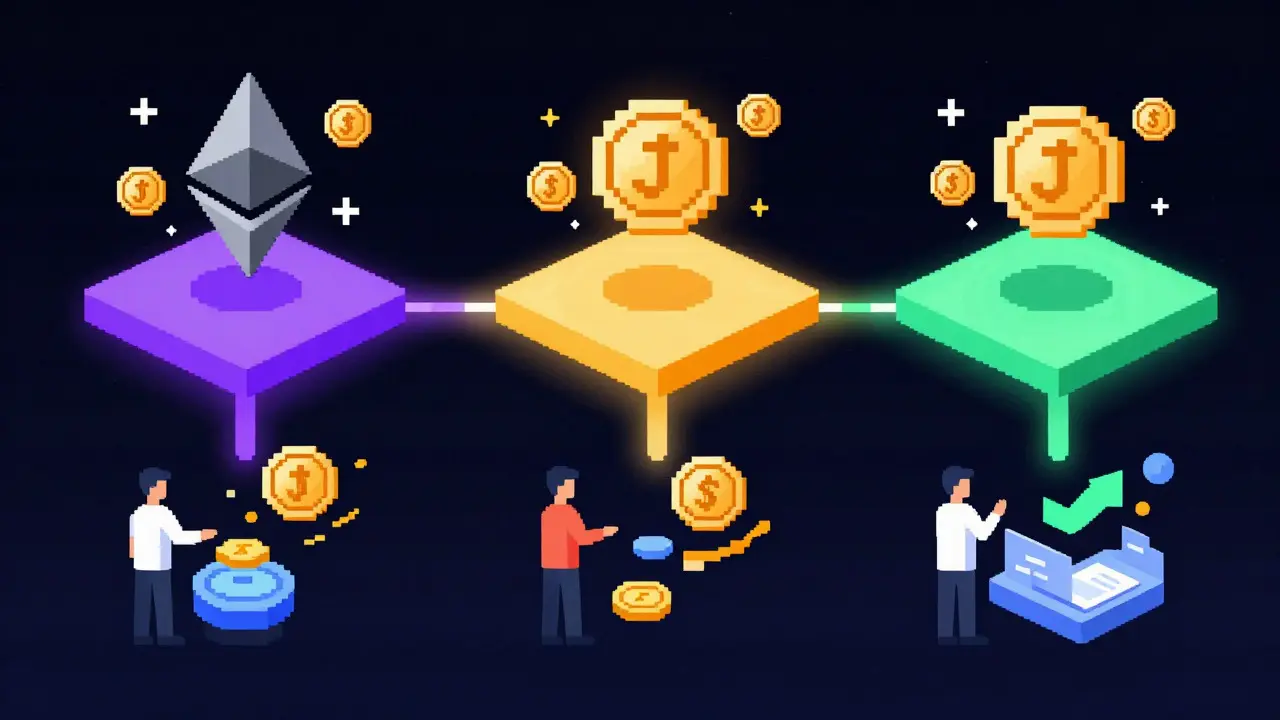
You don’t need to be a coder to use JPYC, but knowing how it works helps you trust it. JPYC operates primarily as an ERC-20 token on the Ethereum blockchain. However, to reduce transaction fees and increase speed, it has expanded to other networks. As of late 2023, JPYC is available on:
- Polygon: Known for low fees and fast transactions.
- Avalanche: Offers high throughput and scalability.
- Gnosis Chain: Popular in Europe for enterprise solutions.
- Astar Network & Shiden Network: Part of the Polkadot ecosystem.
This multi-chain approach is crucial. Ethereum can get expensive during peak times, with gas fees sometimes exceeding the value of small transactions. By supporting Polygon and Avalanche, JPYC makes micro-transactions viable. You can send 100 yen worth of value without paying 50 yen in network fees.
From a smart contract perspective, JPYC uses the UUPS (Universal Upgradeable Proxy Standard) pattern. This sounds technical, but it’s a safety feature. It allows developers to fix bugs or add features to the underlying code without changing the token address you already hold. Your wallet stays the same; the engine under the hood gets updated. Of course, upgradeability carries a slight risk if governance fails, so audits are essential. JPYC contracts have undergone thorough security audits to mitigate this risk.
Real-World Use Cases: What Can You Actually Do With It?
Holding a stablecoin is fine, but spending it is better. Where does JPYC shine? It is designed for two main groups: Japanese consumers and global DeFi users who deal with yen.
1. Everyday Payments in Japan Perhaps the most unique feature of JPYC is its integration with physical commerce. Users can convert their JPYC into Visa prepaid cards, specifically V Preca Gift Cards. This means you can take your crypto holdings and use them at any store in Japan that accepts Visa. It turns abstract blockchain numbers into tangible purchasing power for groceries, electronics, or travel.
2. Decentralized Finance (DeFi) Gateway For Japanese investors, entering DeFi often requires converting JPY to USD, then buying crypto. This exposes them to currency exchange risk. With JPYC, they can stay in yen. They can deposit JPYC into lending protocols or liquidity pools on platforms like Uniswap, Quickswap, or Curve. They earn yield in crypto terms while maintaining exposure to their home currency.
3. Cross-Border Remittances Sending money internationally via traditional banks is slow and expensive. Using JPYC on a fast chain like Polygon allows near-instant transfers across borders with minimal fees, provided the recipient can off-ramp the token back to fiat.
Market Reality Check: Is JPYC Still Relevant?
We need to talk about the numbers. While the technology is sound, the market dynamics have shifted. When JPYC launched in 2021, it saw explosive growth. Today, the landscape is different. As of mid-2026, the total supply stands at approximately 2.14 billion tokens. However, the trading volume has cooled significantly. Daily volumes often fluctuate between $200 and $3,000 USD.
Compare this to USDT or USDC, which trade billions daily. Why the drop? Several factors play a role:
- Regulatory Clarity: Since Japan officially defined stablecoins in June 2023, major banks and fintech companies have entered the space. Competition has increased.
- User Behavior: Many Japanese users prefer centralized exchanges like BitFlyer or Liquid, which handle the KYC (Know Your Customer) process internally. They don’t always need a self-custody token like JPYC.
- Liquidity Fragmentation: Because JPYC is on multiple chains, liquidity is spread thin. Finding deep order books can be harder than on single-chain dominant stablecoins.
Despite lower volume, JPYC remains active on 75 markets. It hasn’t died; it has matured. It serves a niche audience that values privacy, self-custody, and direct blockchain access over the convenience of centralized apps.
| Feature | JPYC Prepaid | USDC (USD Coin) | USDT (Tether) |
|---|---|---|---|
| Pegged Currency | Japanese Yen (JPY) | US Dollar (USD) | US Dollar (USD) |
| Legal Structure (Japan) | Prepaid Payment Instrument | Currency-Denominated Asset (via partners) | Currency-Denominated Asset (via partners) |
| Backing Assets | Bank Deposits, JGBs | Treasuries, Cash Equivalents | Commercial Paper, Treasuries, Cash |
| Primary Networks | Ethereum, Polygon, Avalanche | Ethereum, Solana, Tron, etc. | Tron, Ethereum, BSC, etc. |
| Best For | Japanese residents, JPY-denominated DeFi | Global traders, USD-based savings | High-volume trading, emerging markets |
Risks and Considerations Before Buying
No investment is risk-free. Even though JPYC is a stablecoin, you should be aware of potential pitfalls.
Counterparty Risk: You are trusting the issuer to hold the reserves. While audits help, they are snapshots in time. If the managing company faces insolvency, redemption could be delayed.
Smart Contract Risk: The UUPS proxy pattern allows upgrades. While this fixes bugs, it also means the team retains control over the code. A malicious update could theoretically freeze assets. Always check the latest audit reports before interacting with the contract.
Liquidity Risk: As mentioned, volume is low. If you try to swap a large amount of JPYC for another token on a decentralized exchange, you might experience significant slippage (getting a worse price than expected). Stick to smaller amounts or use centralized exchanges for larger trades.
Regulatory Changes: Japan’s crypto laws are evolving. While JPYC fits the current framework, future regulations could impose stricter requirements on prepaid instruments, potentially affecting usability.
How to Get Started with JPYC
If you decide JPYC fits your needs, here is the general path to acquiring it:
- Choose a Platform: You can buy JPYC directly from the official platform using a bank transfer. Alternatively, look for it on decentralized exchanges like Uniswap (for Ethereum/Polygon) or Curve.
- Set Up a Wallet: You need a non-custodial wallet like MetaMask or Trust Wallet. Ensure your wallet supports the network you are using (e.g., switch to Polygon network if buying on Polygon).
- Complete KYC: Since JPYC is a prepaid instrument tied to identity, you will likely need to verify your identity to link your bank account.
- Transfer Funds: Send JPY from your bank account. Once confirmed, the equivalent amount of JPYC tokens will be minted and sent to your wallet address.
- Use or Hold: From here, you can hold it as a savings vehicle, swap it for other cryptos, or convert it to a Visa prepaid card for spending.
Final Thoughts on JPYC
JPYC Prepaid is a fascinating example of how regulation shapes innovation. It isn’t the flashiest token, nor does it promise infinite returns. It is a utility tool. For Japanese users who want the freedom of blockchain without the headache of currency conversion, it offers a streamlined solution. For global users, it provides exposure to the yen in a digital format.
While its trading volume has settled into a quieter rhythm compared to its 2021 launch, its fundamental purpose remains valid. In a world where fiat currencies dominate daily life, having a reliable, compliant, and multi-chain stablecoin for the third-largest economy in the world fills a necessary void. Just remember to do your own due diligence, check the latest reserve reports, and never invest more than you can afford to manage.
Is JPYC safe to hold?
JPYC is considered relatively safe because it is backed 1:1 by liquid reserves like bank deposits and Japanese Government Bonds. However, like all crypto assets, it carries counterparty risk (trust in the issuer) and smart contract risk. It is safer than algorithmic stablecoins but requires monitoring of the issuer's financial health.
Can I use JPYC outside of Japan?
Yes, JPYC can be held and traded globally on supported blockchains like Ethereum and Polygon. However, its primary utility, such as converting to Visa prepaid cards, is optimized for the Japanese market. International users may find limited off-ramping options compared to USD stablecoins.
Why is JPYC classified as a prepaid instrument?
Until June 2023, Japan did not have a clear legal definition for stablecoins, restricting issuance to banks. To operate legally, JPYC was structured as a Prepaid Payment Instrument under the Payment Services Act, allowing it to function similarly to a digital gift card while operating on the blockchain.
Which blockchain networks support JPYC?
JPYC is available on multiple networks including Ethereum, Polygon, Avalanche, Gnosis Chain, Astar Network, and Shiden Network. This multi-chain presence helps users avoid high gas fees associated with the Ethereum mainnet.
Who backs JPYC financially?
JPYC received early backing from Circle Ventures, the creator of USDC. Its reserves are managed through bank deposits and Japanese Government Bonds, ensuring that each token is fully collateralized by real-world assets.
Nick Darring
August 14, 2026 AT 11:19Look, I get why people are skeptical about everything crypto-related these days, but dismissing JPYC entirely feels like throwing the baby out with the bathwater because you don't trust the plumbing. The fact that it's structured as a prepaid instrument under Japanese law isn't a bug, it's a feature that allows it to exist at all when other options were legally grey or non-existent for years. Sure, it might feel clunky compared to USDT, but if you're actually living in Tokyo and want to use DeFi without converting to dollars every single time, this solves a very specific headache that Americans probably can't even comprehend because they live in the land of the dollar hegemony. It’s not about being flashy, it’s about utility within a restrictive framework, and frankly, I respect the hustle of navigating those regulations rather than just ignoring them like some offshore entities do.
Eden Tadesse
August 14, 2026 AT 18:37i thnk its cool but the volume is so low tho 😅
Rita Dutta
August 16, 2026 AT 18:13The essence of JPYC is not merely financial but existential, reflecting the soul of a nation trying to digitize its identity without losing its cultural moorings. To dismiss it as low volume is to misunderstand the quiet dignity of stability in a chaotic world. The yen has always been a currency of precision, and JPYC embodies that spirit in the digital ether, where liquidity is not just numbers but a testament to trust woven through code and law. Perhaps the low volume is a sign of maturity, a silent meditation on value rather than the noisy speculation of meme coins that dance on the graves of volatility. One must look deeper, beyond the superficial metrics of daily turnover, to see the philosophical underpinning of a currency that refuses to play the game of chance.
Paul Smith
August 17, 2026 AT 13:55Hey everyone! 👋 Just wanted to say that JPYC is super useful for my friends in Osaka who love using Visa cards for groceries 🍱. It’s awesome how they can swap crypto for real-world stuff easily! 🇯🇵✨
Rodmun Tarnowski
August 17, 2026 AT 14:44Indeed! It is truly remarkable how such a specialized tool can bridge the gap between traditional banking and decentralized finance. The integration with Visa prepaid cards is a brilliant move, allowing users to participate in the modern economy without sacrificing the stability of their home currency. This is exactly the kind of innovation we need to see more of, provided it remains compliant and secure!
Ed Mitchell
August 18, 2026 AT 16:01Don’t be fooled by the friendly emojis. This is all part of a grand scheme to track every yen you spend. The 'prepaid instrument' classification is a Trojan horse for total surveillance. They want to know what you buy, when you buy it, and why you bought it. Circle Ventures backing it? That’s just the tip of the iceberg. Trust no one.
Michael Mostyn
August 19, 2026 AT 00:38One must consider the ontological status of a token that claims to represent value yet exists only as data. Is JPYC truly money, or is it merely a promise wrapped in code? The legal structure as a prepaid instrument suggests a duality: it is both an asset and a liability, depending on whom you ask. This ambiguity is fascinating from a philosophical standpoint, raising questions about the nature of trust in a digital age where intermediaries are replaced by algorithms and audits.
Erica Johnson
August 20, 2026 AT 05:51Actually, the UUPS proxy standard is a huge red flag for anyone who knows anything about smart contract security. :) If the team can upgrade the code, they can theoretically freeze your assets or change the rules overnight. It’s not 'safety', it’s centralized control disguised as flexibility. People should be worried.
Ken G
August 21, 2026 AT 13:43typical crypto bro ignorance. the system is rigged anyway. jpyc is just another tool for the elite to launder money while pretending to help the little guy. wake up sheeple.
Lorraine Surringer
August 23, 2026 AT 06:08You’re missing the point entirely, dear. It’s not about 'laundering', it’s about accessibility for regular folks in Japan who want to use DeFi without dealing with USD conversion fees. Your cynicism is exhausting and frankly, unhelpful. Let people enjoy their financial tools without dragging down the mood with your conspiracy theories.
Amor Jordan
August 23, 2026 AT 11:20I really appreciate the detailed breakdown here. It’s comforting to know that there are options for people outside the US-centric crypto bubble. The idea of using JPYC for cross-border remittances sounds incredibly practical, especially for families sending money back home. It’s nice to see technology serving real human needs rather than just speculation.
Matt Kay
August 24, 2026 AT 09:02low vol though
Dave Kjendal
August 26, 2026 AT 04:34It’s dead. Move on. No one uses it except bots and the founders. Waste of time reading this.
Kat Bennett
August 28, 2026 AT 04:07I’ve been watching the space for a while now, and while the volume isn’t what it was in 2021, that doesn’t mean it’s useless. Sometimes, stability is boring, and that’s a good thing. For someone like me who just wants to park some yen in a DeFi pool without worrying about FX risk, JPYC offers a niche solution that works quietly in the background. It’s not for everyone, sure, but for those who need it, it’s a reliable tool. I prefer to observe and let the market decide rather than jumping on bandwagons.